Start with the chart
Every plan with the same letter pays the same benefits, whichever company sells it. That makes the chart the fairest place to begin. The columns for G and N, plus the note under the chart about High Deductible G, tell most of the story for anyone new to Medicare.
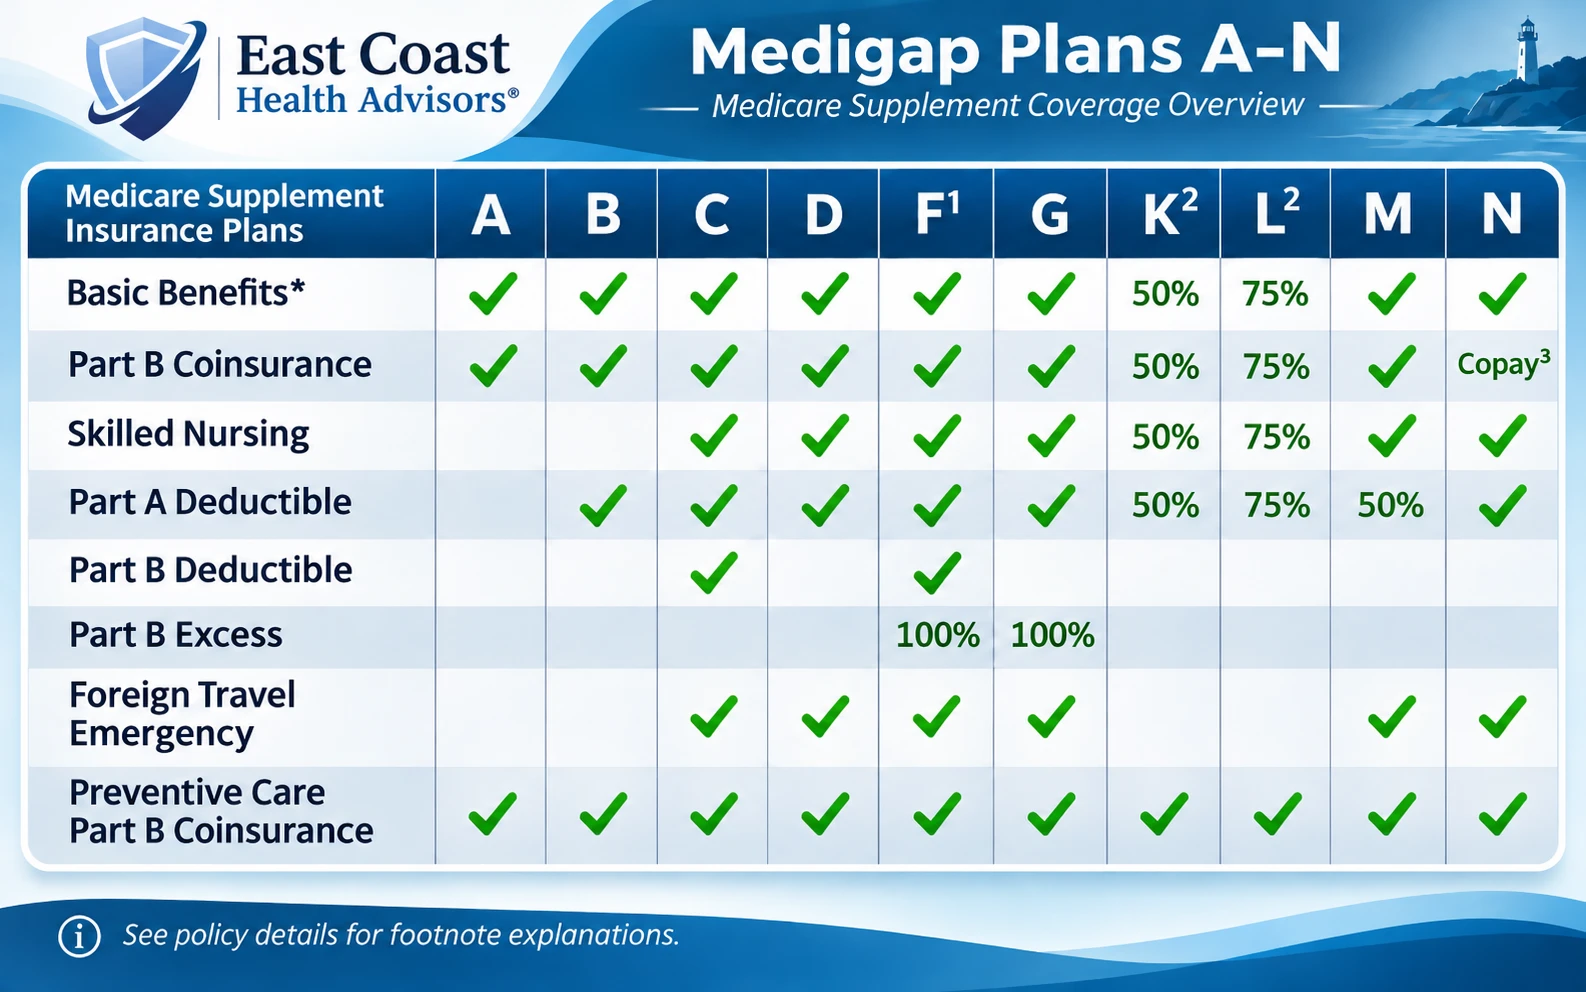
Plan F still appears on the chart because people who were eligible for Medicare before 2020 can keep or buy it. If you are turning 65 now, your realistic choices are G, N and High Deductible G, with Plans A, B, K, L and M available but less common.
Fewest bills
Plan G
Think of Plan G as the near complete option. In 2027 you cover the first $292 of Part B charges yourself, and from that point the plan handles the rest of your Medicare approved bills for the year. That includes the $1,776 hospital deductible each benefit period and any excess charges a doctor bills above Medicare's rate.
Upsides
- Predictable costs after one small deductible
- Covers Part B excess charges
- Foreign travel emergency coverage
Tradeoffs
- Highest premium of the three in most cases
- You still pay the Part B deductible
- No drug, dental or vision coverage
Lower premium, small copays
Plan N
Plan N copies Plan G for the big items: inpatient stays, skilled nursing and the Part A deductible. Where it parts ways is everyday care. A doctor visit may come with a copay of up to $20, an ER trip that ends without admission may cost up to $50, and any Part B excess charge stays with you, as does the $292 Part B deductible.
Upsides
- Usually a lower premium than Plan G
- Same hospital and skilled nursing coverage
- Foreign travel emergency coverage
Tradeoffs
- Copays at the doctor and emergency room
- Part B excess charges are yours
- More small bills to track
Lowest premium, big year protection
High Deductible Plan G
HDG is Plan G with a $3,050 deductible. Until you have paid $3,050 in Medicare approved costs in 2027, you pay them yourself. After that, it covers the same gaps as regular Plan G for the rest of the year. The Part B deductible counts toward the $3,050.
Upsides
- Lowest premium of the three in most cases
- Full Plan G coverage after the deductible
- A known ceiling on approved costs each year
Tradeoffs
- Up to $3,050 out of pocket before it pays
- A heavy medical year costs more
- The deductible can rise each year
How we help Germantown clients choose
We start with how you use care. Someone who sees a cardiologist in Rockville every quarter and wants no surprises often leans toward Plan G. Someone healthy who rarely sees a doctor may prefer Plan N or High Deductible G and keep the premium difference in savings. Results vary by person, so we run the numbers both ways using quotes from the carriers we represent.
We also look past this year's price. Some carriers raise rates more often than others, and Maryland allows different pricing methods, which we explain on our Germantown Supplement costs page. Because Maryland's birthday rule lets you move to equal or lesser benefits each year, starting on Plan G keeps the most doors open later.
Plan questions
Which plan do most Germantown clients choose at 65?
There is no single right answer. Plan G suits people who want the fewest bills, Plan N suits people comfortable with small copays in exchange for a lower premium, and High Deductible G suits people who want catastrophic protection at a lower monthly cost. We compare all three with real quotes.
Can I change from Plan G to Plan N later?
In Maryland, the yearly birthday rule lets you move to equal or lesser benefits without health questions in the 30 days after your birthday, so moving from G to N is usually possible. Moving from N up to G outside a guaranteed window may require underwriting.
Do these plans cover care when I travel?
Plans G, N and High Deductible G all include foreign travel emergency coverage, which pays 80 percent of approved emergency care abroad after a $250 deductible, up to the plan's lifetime limit. Within the U.S., you can use any provider that accepts Medicare.
Compare G, N and HDG with real quotes
We price all three from the carriers we represent and show you the yearly math.
Book an appointmentRather call?
Our licensed team answers during business hours. Or email [email protected] and our licensed team will write back.